The limits
- Stock at cost
- Up to £250,000
- Business interruption
- 24-month indemnity period
- Public liability
- £5m
- Employers' liability
- £10m
Stock, glass and the takings you lose while the doors are shut.
Shop and premises
from £410 a year
4.9 (612)Cover for independent shops, cafés, salons and offices: buildings or tenant's improvements, stock, shopfront glass, business interruption and liability.
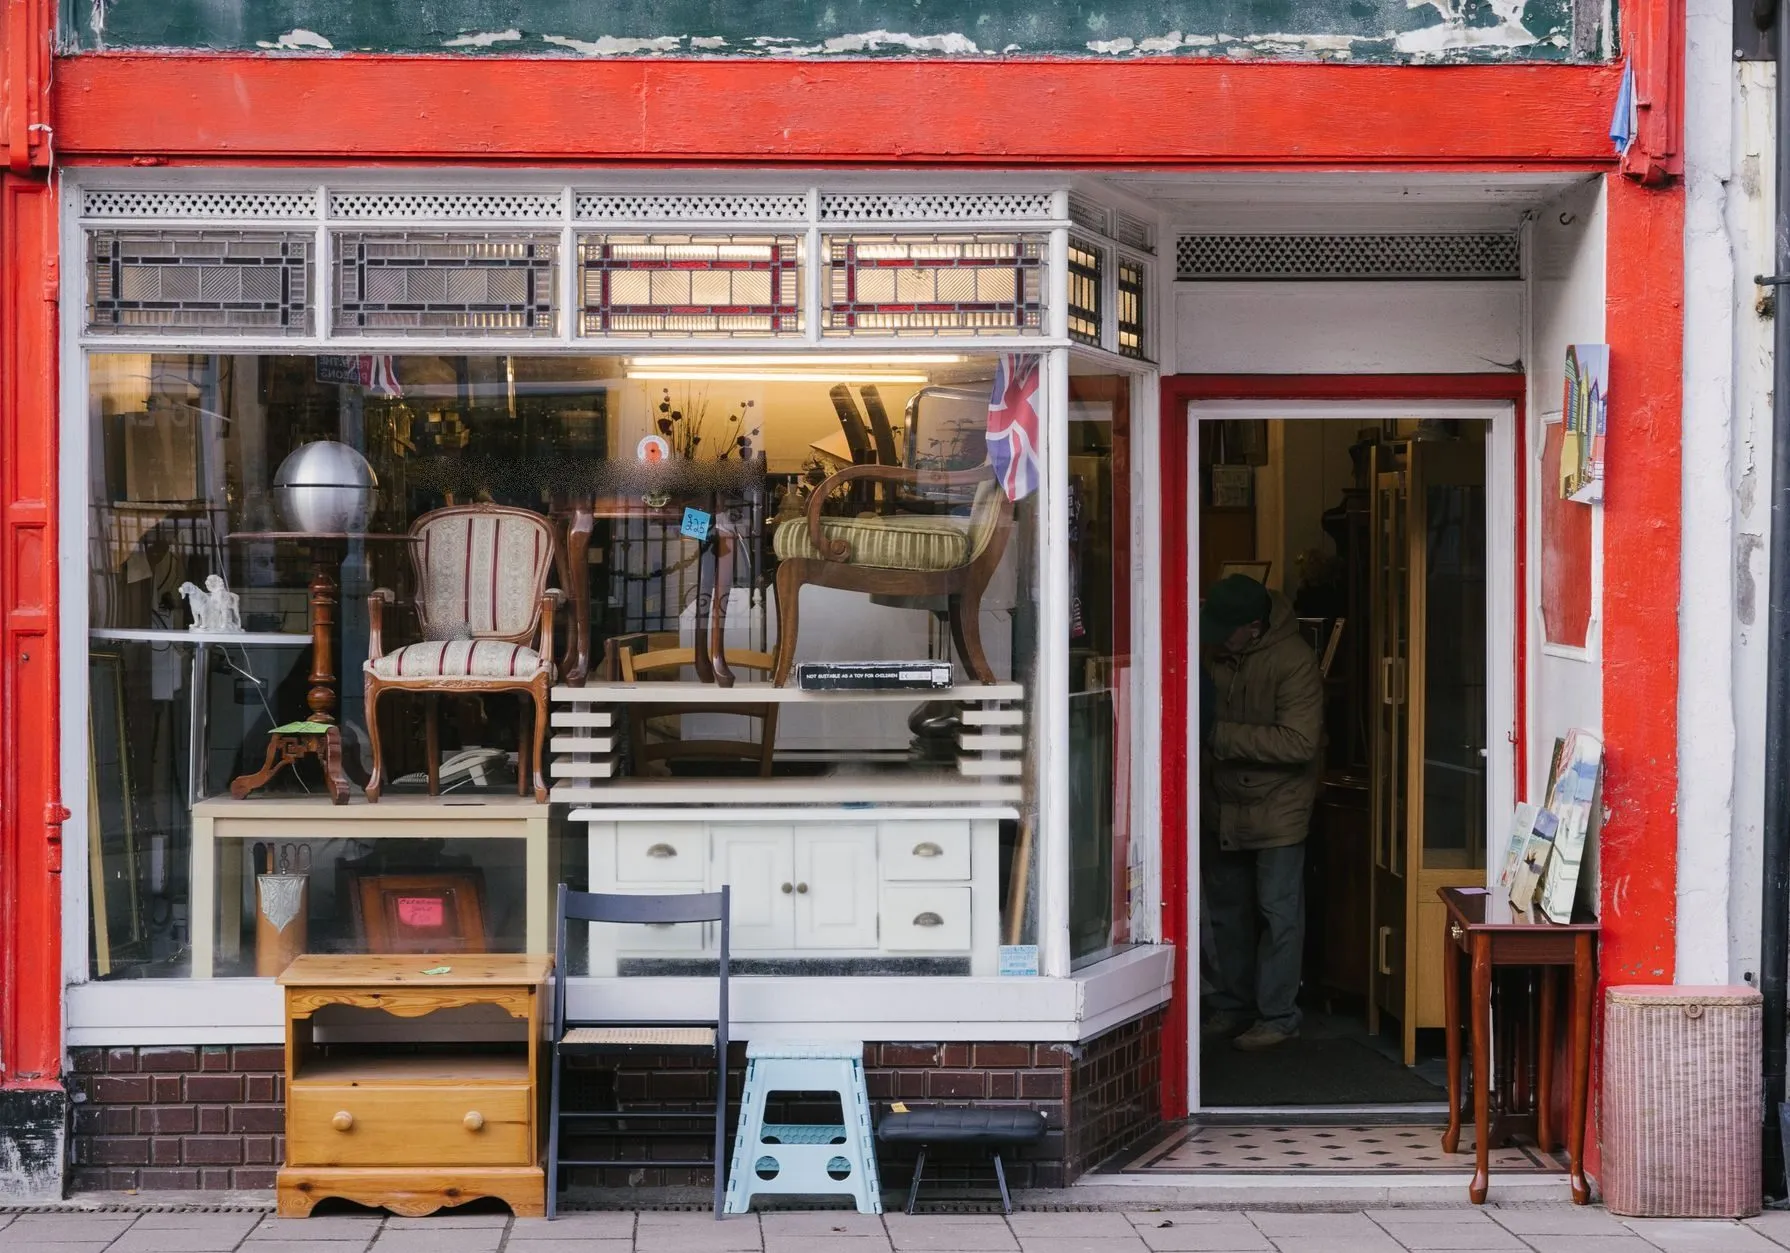
Who it suits. Independent retailers, cafés, salons and offices in a single unit, owned or leased, with or without a flat above.
Standard excess £500. The price shown is typical for a plain risk, not a quote.
What is covered
- Stock at cost, with a 30% seasonal uplift through December
- Shopfront glass, including replacement signwriting
- Loss of trade while you cannot open, for up to two years
- Public liability to £5m, employers' liability to £10m
- Frozen and chilled stock when a unit fails overnight
What is not
- Money left on the premises overnight above £500
- Theft without forced entry: a walk-in is not a break-in
- Stock kept outside unless agreed on the schedule
How we place it
The stock and the glass are the parts every shop policy covers. The part most shops find out about late is business interruption: the money you do not take while the doors are shut after a fire, a flood or a burst pipe upstairs.
We set the interruption cover on your real gross profit and an indemnity period long enough to cover a refit, not the three months some policies default to. For a café that has to replace a kitchen, three months is rarely enough.
If you lease the unit, check the lease. It will say who insures the building and the glass, and we will make sure the policy matches it rather than doubling up.
A claim we handled
Shopfront glass, and three days shut
Put through on a Saturday night. The glass was £2,260; the three days of lost trade were £1,850, and that is the half most shop policies leave out.
- Insurer paid
- £3,610
- Excess
- £500
- Days to settle
- 9