Independent brokers at 14 Tanner’s Yard, Ludlow
Insurance for the house, the van and the farm, placed by a broker you can ring.
We take your risk to 21 insurers, explain the two or three worth having, and handle the claim if the worst happens. Across Shropshire, Herefordshire and mid-Wales since 1974.
What do you need to insure?
Pick one to start a quote request. Two minutes, then a broker rings you.
- Home from £190/yr
- Landlord from £240/yr
- Van from £640/yr
- Fleet from £2,100/yr
- Shop from £410/yr
- Trade from £260/yr
- Farm from £1,400/yr
Or ring the office on 01632 960 742
-
Whole of market
21 insurers on the panel, and underwriters by phone for anything unusual.
-
We handle the claim
One number, 24 hours, answered by a broker who can see your policy.
-
Every renewal re-broked
Back out to the market each year, not rolled over with a rise.
-
Commission on the invoice
What we earn is written down before you pay, every time.
What we insure
What can we insure for you?
Seven kinds of cover for the homes, trades and farms of the Marches. Every price is a typical annual premium for a plain risk; yours comes after one conversation.
Since 1974
Nine brokers, one office, and about 2,400 policies we know by name
No call centre and no insurer owns us. When you ring, the person who answers placed your policy, and will be there when you claim on it.
- Insurers on the panel
- 21
- Claims settled last year
- 311
- Average days to settle
- 9
How a quote works
From first call to cover in about three working days
-
Tell us what it is
Two minutes online or ten on the phone. The renewal notice you already have is usually enough.
-
We go to market
Your risk goes to the insurers on our panel that write it well, and to a specialist if it needs one.
-
You get it in writing
Two or three options, side by side, with the excess and the exclusions in plain English. Usually within three working days.
-
We stay on it
Mid-term changes, the claim if there is one, and the renewal next year. Same office, same people.
Quote request
Ask for a quote in about two minutes
Tell us what it is, when it renews and when to ring. We show a typical premium range for similar risks, then a broker calls at the time you choose with real figures.
- No obligation, and nothing is sent to an insurer until you say so
- Your renewal notice is the most useful thing to have to hand
- Unusual risks welcome: thatch, HMOs, young drivers, spray booths
Why a broker
Broker, comparison site or straight to the insurer?
All three can sell you a policy. The difference shows up at renewal, and again on the day you claim.
| Question | Kedworth & Quire | Comparison site | Going direct |
|---|---|---|---|
| Insurers who see your risk | 21, plus specialists by phone | Those that pay to be listed | One |
| Thatch, listed, unoccupied, HMO | Placed by phone | Usually declined | Sometimes |
| Who handles your claim | Us, on your side | The insurer’s call centre | The insurer’s call centre |
| At renewal | Re-broked across the market | You search again | Rolled over, often with a rise |
| What it costs you | Commission, shown on the invoice | Built into the price | Built into the price |
Claims we handled
311 claims settled last year. Here are four of them.
Real figures from the file, shared with permission and initials only.
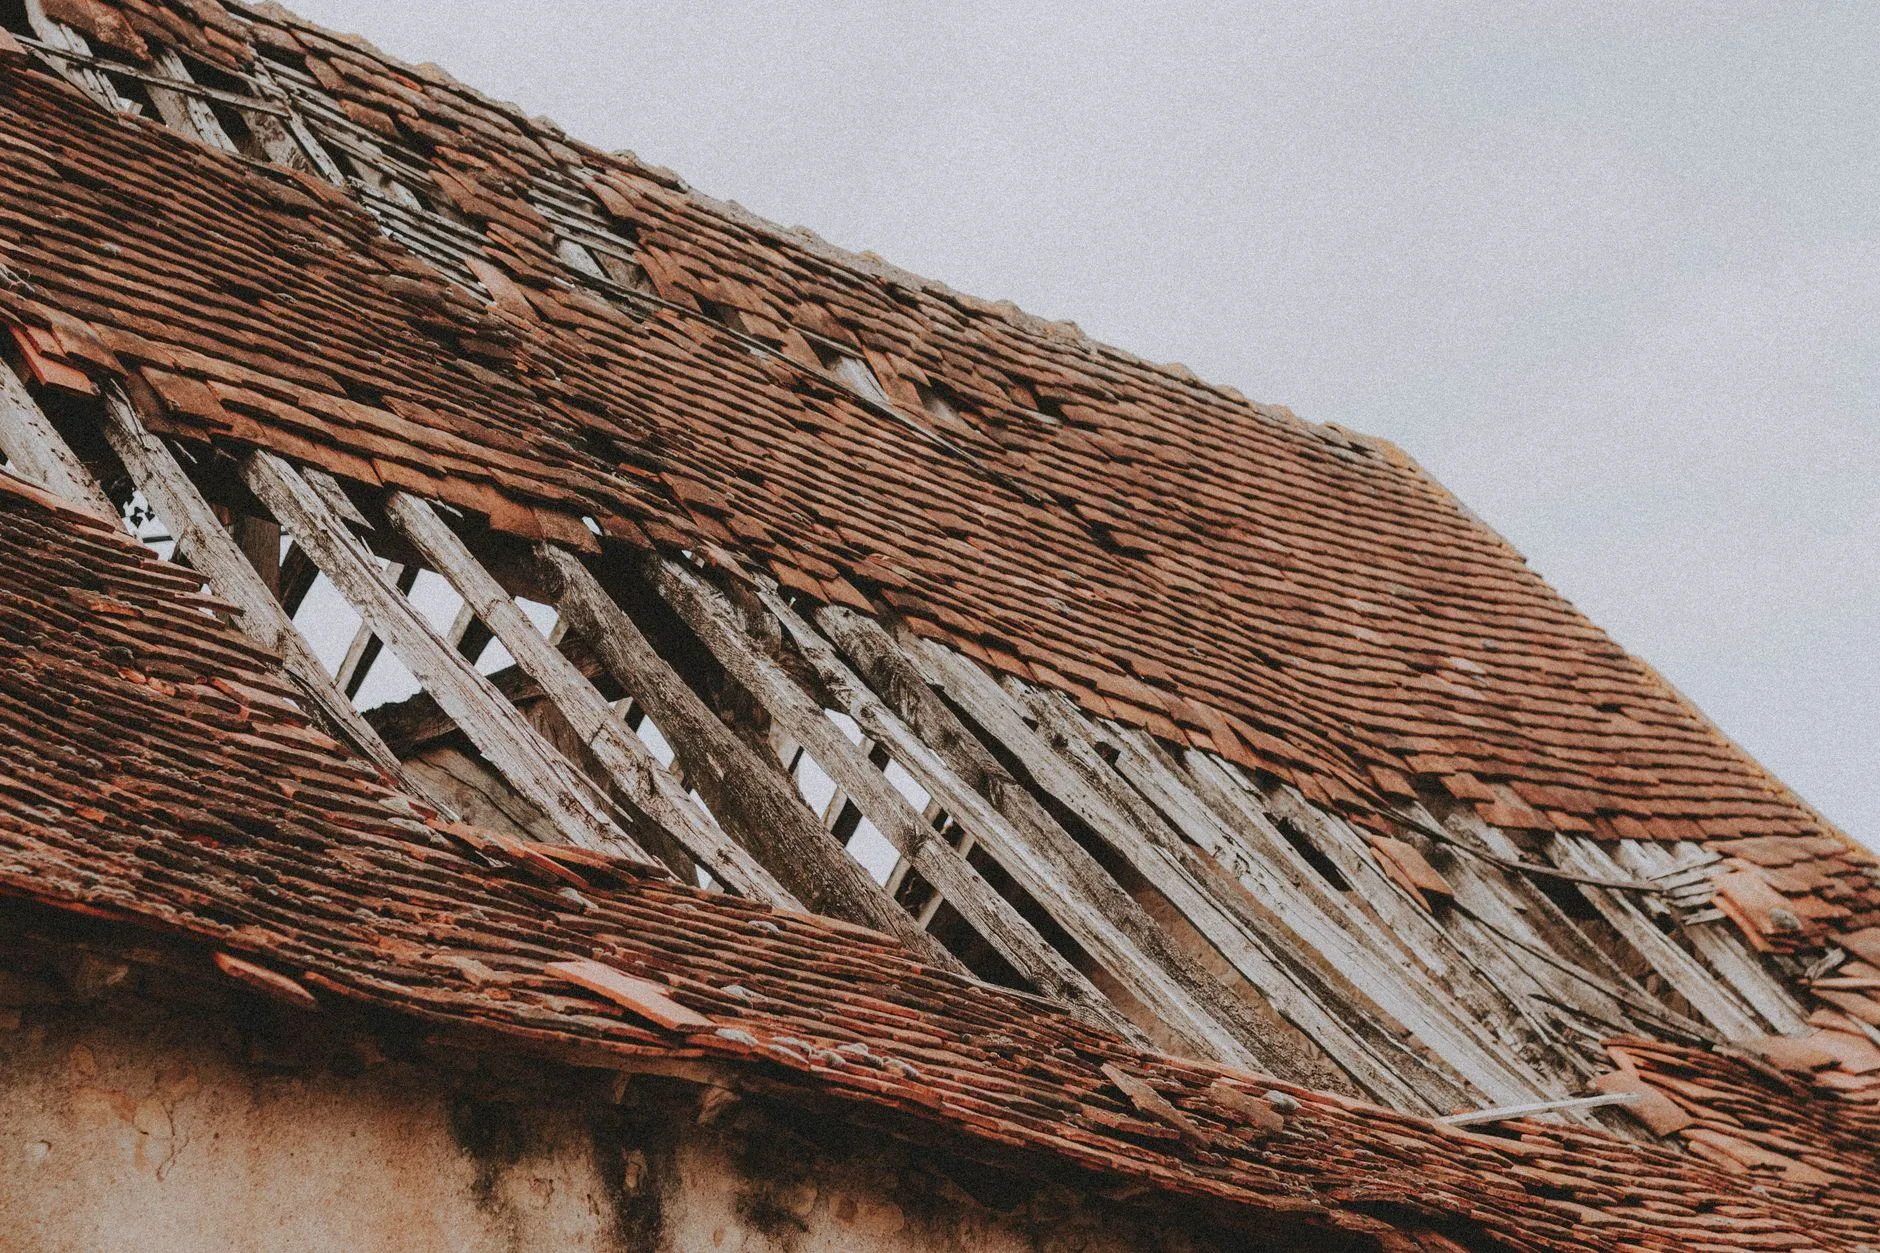
Storm took the roof off a stone barn
Forty square metres of tiles gone in February. We had the barn on the schedule at rebuild cost, not market value, so the reroof was paid in full.
- Insurer paid
- £18,400
- Excess
- £1,000
- Days to settle
- 24
Ceiling down after a leak upstairs
Tenant below had to move out for three weeks. The policy paid the repair and the lost rent, and the tenant’s hotel was sorted before the end of the day.
- Insurer paid
- £6,980
- Excess
- £350
- Days to settle
- 14
Tools taken from a locked van
Side door forced overnight on a job in Hereford. Receipts for about half of it; the tools schedule we had set up at renewal covered the rest.
- Insurer paid
- £2,640
- Excess
- £500
- Days to settle
- 6
Shopfront glass, and three days shut
Put through on a Saturday night. The glass was £2,260; the three days of lost trade were £1,850, and that is the half most shop policies leave out.
- Insurer paid
- £3,610
- Excess
- £500
- Days to settle
- 9
Guides
The small print, in plain English
Home and business · 4 min read
Underinsurance and the average clause
If the sum insured is short, every claim is cut by the same proportion, even when the loss is far smaller than the cover.
Claims · 5 min read
Storm or flood? Why the word on the claim form matters
Two claims from the same night can be settled completely differently depending on whether the water came down or came in.
Vehicles and trade · 3 min read
Are the tools in your van actually insured?
Most van policies exclude tools, or cover them only in daylight. Four questions to ask before the side door is forced.
Questions
What people ring us to ask
Anything else, the office answers the phone from 8.30am.
Home
Can you insure a thatched or listed house?
Yes. Thatch, listed frontages, timber frames and flat roofs are most of what we place by telephone. We send the details to specialist underwriters who price the building rather than the postcode.
What is the difference between rebuild cost and market value?
Buildings cover pays what it costs to rebuild, which is often more than the house would sell for: scaffolding, a party wall award and a skip are not in the asking price. We check the figure with you at every renewal.
My house is empty while I sell it. Am I still covered?
Most policies restrict cover once a house is unoccupied for 30 to 60 days. Tell us before that date and we will either extend the cover or place an unoccupied property policy.
Business
What is business interruption cover, and do I need it?
It pays the profit you lose while you cannot trade after an insured event, such as a fire or a flood. For a shop or café it is usually the largest part of a claim and the part most often missing.
Do I need employers’ liability if I only take on labourers now and then?
Yes. It is a legal requirement the moment anyone works for you, even for a day, and the fine for not holding it is charged per day. We add it mid-term in one phone call.
Can you insure a farm with a diversification, such as a farm shop or glamping?
Yes. The farm, the shop and the pods go on one policy, with the public liability set for visitors rather than for a working yard.
Vehicles
Are the tools in my van covered overnight?
Only if the policy says so and the van is locked. Many van policies exclude tools altogether. We add a tools section with a stated limit, usually £3,000 to £10,000 per vehicle.
Can drivers under 25 go on a fleet policy?
Yes, as named drivers. It changes the price, but it is far cheaper than a separate policy for one young driver, and it keeps every vehicle on one renewal date.
How many vehicles make a fleet?
Two is enough for most insurers. From three vehicles a fleet policy is almost always cheaper than separate policies, and much less paperwork.
Send us your renewal notice before it rolls over.
We will take it back out to the market and tell you, in writing, whether you can do better. If you cannot, we say so.